FinancialMirror.ca

START WITH A REAL QUESTION

Life doesn’t fit into
a single spreadsheet.

Real decisions involve taxes, costs and tradeoffs. These fictional households show how we bring the details into the conversation—even when the numbers challenge the original plan.

01 / RETIREMENT
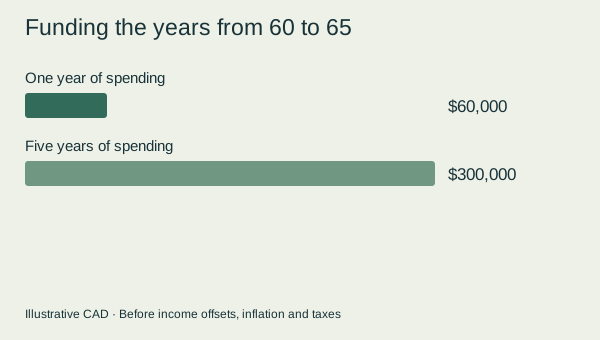
One year of spending: $60,000. Five years: $300,000.

MEET MAYA & DANIEL · AGES 52 & 54

“Could we retire sooner
and still feel secure?”

They have savings and a paid-down mortgage. What they don’t have is a clear picture of how long their money needs to last.

Explore their planning conversation

What we would calculate

The chart isolates one question: five years of $60,000 annual spending is $300,000. This is a gross spending bridge, before pensions, other income, inflation and taxes. A full comparison would calculate household cash flow, pensions and withdrawals.

What we would test

Lower returns, higher living costs, a longer retirement and the financial impact of one partner dying first.

The decision we would guide

Whether retiring earlier, working part-time or adjusting spending offers the balance they value.

Talk about your retirement →
02 / BUSINESS OWNERS
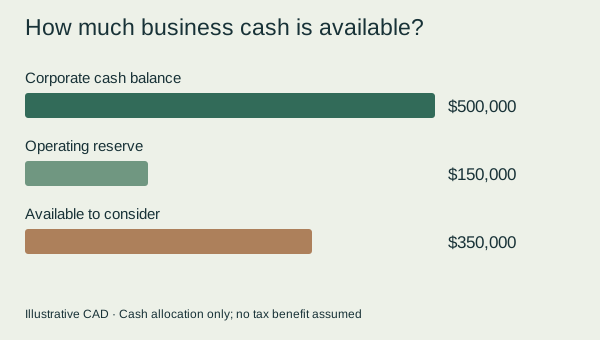
Cash $500,000 less reserve $150,000 leaves $350,000.

MEET AMIR · AGE 46

“My business is growing.
Is my personal future?”

Money is building inside his corporation. He wants to understand how it could support his family, retirement and long-term goals.

Explore his planning conversation

What we would calculate

The example starts with $500,000 corporate cash and sets aside a $150,000 operating reserve: $350,000 remains to consider for other goals. This is cash allocation, not a recommended strategy. We would compare suitable options with taxes, liquidity and cash-flow effects included.

What we would test

Changes in business cash flow, investment returns and borrowing costs where a strategy involves financing.

The decision we would guide

How to balance accessible cash, future income, protection and estate goals alongside his accounting and legal professionals.

Talk about your business and future →
03 / FAMILY PROTECTION
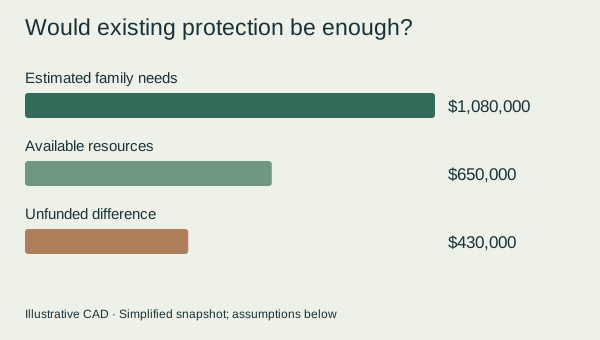
Needs $1,080,000 less resources $650,000 leaves a $430,000 gap.

MEET SOPHIE & ALEX · TWO YOUNG CHILDREN

“Would our family be okay
if life changed tomorrow?”

A mortgage, two incomes and education goals. They want to know what their existing protection would actually cover.

Explore their planning conversation

What we would calculate

Example needs: $60,000 annual support for 10 years ($600,000), $400,000 mortgage repayment and $80,000 education funding: $1,080,000 total. Resources: $150,000 available savings plus $500,000 existing insurance: $650,000. Difference: $430,000. This simplified snapshot excludes discounting, inflation, taxes, survivor income and benefits. A full assessment would account for these and avoid counting repaid mortgage costs again in support needs.

What we would test

Loss of either income, changing childcare needs and different protection budgets.

The decision we would guide

The amount and type of protection that fits their needs, affordability and time horizon, with alternatives explained.

Talk about your family’s priorities →

All chart amounts are fictional CAD examples, not completed financial plans or guaranteed outcomes. Open each planning conversation to see the context and assumptions.

Does one of these questions
sound like yours?

Let’s talk about your situation.

Start a conversation ↗